

Wheel Loader Market Trends 2026: New Sales Cool While Used Demand Climbs
If you're shopping for a wheel loader right now, the market you're buying into looks different than it did a year ago — and the numbers tell a pretty clear story about where contractors are actually putting their money. New wheel loader financing volume has pulled back meaningfully, used demand is climbing, and prices have held up in a way that says a lot about how contractors are managing capital right now. Here's what the current data actually shows, and what it means for your next purchase decision.
Why This Data Matters to You, Not Just Analysts
It's easy to treat market-share and volume statistics as background noise — numbers for industry analysts, not something that changes what you actually do on your next equipment purchase. That's a mistake. Financed transaction data is one of the most honest signals available about where real buyers are putting real money, because unlike a manufacturer's press release or a dealer's sales pitch, it reflects actual decisions contractors made with their own capital. When new financing volume drops 12.8% while used volume climbs 4.8%, that's thousands of individual contractors independently reaching similar conclusions about how to manage their equipment budgets right now — and that collective judgment is worth paying attention to before you sign your own purchase agreement.
New Financing Volume Is Down, Used Is Up
Financed new wheel loader unit volume fell roughly 12.8% year-over-year over the most recent 12-month tracking period, while financed used wheel loader volume rose about 4.8% over the same span, according to Equipment World's market-pulse tracking of financed equipment transactions. That's not a small move — it's a real shift in how contractors are deciding to acquire wheel loaders, and it lines up with a pattern we're seeing across other equipment categories too: tighter capital discipline is pushing more buyers toward used inventory rather than new, even as overall construction activity has stayed reasonably steady in most regions.
BFC analysis of Equipment World's wheel loader financing volume data, 2025–2026 — illustrative chart built from published market-pulse figures, not an official industry publication.
Why the Shift Toward Used
Interest rate environment: financing costs on new equipment remain a real factor in monthly payment math, pushing budget-conscious buyers toward lower-principal used purchases.
Solid used inventory quality: with average used wheel loader age sitting around 7.4 to 8.1 years, there's a healthy supply of well-maintained mid-life machines still under reasonable hour counts.
Price stability in the used market: average used wheel loader prices have held in a fairly tight band — roughly $150,700 to $158,000 across recent quarters — giving buyers price predictability that makes budgeting easier.
Project timing uncertainty: contractors facing uncertain bid pipelines are understandably more comfortable committing to a lower-cost used purchase than a full-price new machine.
Who's Actually Winning New Wheel Loader Business
Despite the overall pullback in new volume, the competitive picture among manufacturers has stayed fairly stable. Caterpillar leads new financed wheel loader market share at roughly 22.5%, with John Deere close behind at about 21.1%. Komatsu holds a solid third position at 12.4%, followed by Case CE at 9.9% and Volvo CE at 8.3%. That top-two grouping being so tight is notable — Deere has clearly closed most of the gap with CAT in the wheel loader category, which wasn't always the case in this class.
BFC analysis of Equipment World's new wheel loader financing market share data — illustrative chart built from published market-pulse figures, not an official industry publication.
Komatsu holds the third-largest new wheel loader financing share in the current market data, with models like the WA320-8 among the best-selling units in the class. Image: Komatsu.
What the Best-Selling Models Tell Us
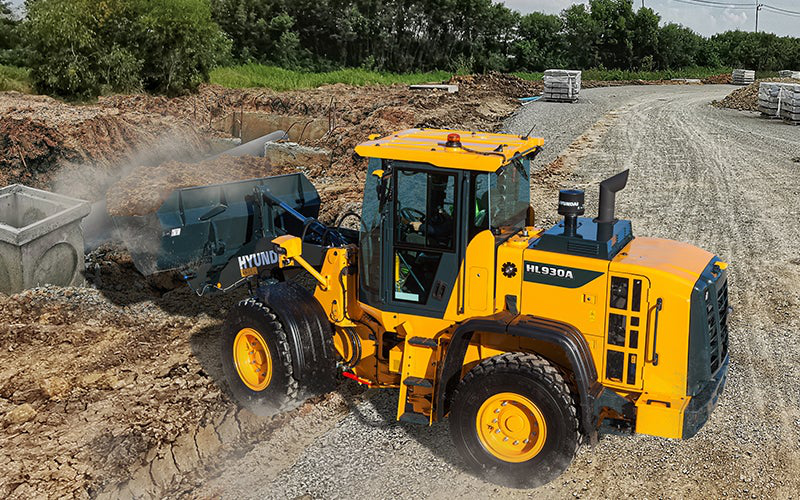
The top-selling new models in the most recent tracking period were the Komatsu WA320-8, John Deere 624 P-Tier, and Case 321F — all mid-size, general-purpose loaders rather than specialty configurations. That's a meaningful signal: contractors who are buying new right now are buying the workhorse machine, not the premium technology-loaded flagship. It suggests new-equipment buyers in the current market are prioritizing reliability and versatility over the latest feature set, which tracks with tighter capital discipline generally. If you're deciding between a standard-configuration loader and a heavily optioned one like CAT's 950 GC or Hyundai's extended-reach HL960A XT, it's worth honestly assessing whether you'll use the extra capability enough to justify the premium in the current financing environment.
The Age and Condition Picture in the Used Market
Average used wheel loader age in current transaction data sits between roughly 7.4 and 8.1 years, which puts most of what's changing hands squarely in the mid-life window — old enough to have shed the steepest early depreciation, young enough to still have substantial productive life ahead of it. That's a genuinely good window for buyers: you're not paying new-equipment premium pricing, but you're also not gambling on a machine near the end of its economic life. It's worth having a mechanic or your dealer run a real inspection on hours, undercarriage wear, and hydraulic condition before committing, since "average age" data describes the market, not any individual machine you're looking at.
Price stability in that used band — the roughly $150,700 to $158,000 range recorded across recent quarters — also gives buyers something valuable: predictability. When used prices aren't swinging wildly quarter to quarter, it's easier to budget a purchase with confidence that you're not overpaying at a market peak or catching a temporary dip that won't hold.
What This Means at Auction
Auction activity backs up the used-market strength story. The highest recorded auction sale in the most recent tracking period was $555,000 for a CAT 988K with just under 7,000 hours, sold in Phoenix — a striking number for a used machine, and a reminder that quality CAT iron continues to command premium prices at auction. Caterpillar claimed 17 of the top 20 auction price spots in the same period, underscoring the resale-value advantage that shows up consistently across the used wheel loader market and reinforcing why so many contractors are willing to pay a premium for the CAT badge even on the used side.
Reading the Deere-vs-CAT Gap Correctly
The near-tie between CAT and Deere in new wheel loader share deserves a second look, because it's not just noise — it reflects Deere's sustained investment in its P-Tier construction lineup paying off in a category that used to be more clearly CAT-dominated. For contractors, that competitive tightness is good news: it means both manufacturers have strong incentive to keep pricing, financing promotions, and dealer support sharp to win and retain business. If you're cross-shopping new, it's worth getting real quotes from both brands' dealers rather than assuming one has a clear edge — the market data says they're closer than conventional wisdom might suggest.
What This Means for Your Next Purchase
None of this data says new wheel loaders are a bad buy — it says the market has shifted toward more deliberate capital decisions, and financing terms matter more than ever in making either a new or used purchase pencil out. A well-structured loan on a used machine with strong remaining service life can be just as smart a decision as new financing on a workhorse model, depending on your project pipeline and how long you plan to keep the machine. For a deeper look at how the broader used-equipment auction market is shaping financing decisions across equipment categories, see our 2026 used equipment auction data breakdown.
Regional Variation Is Real
National figures like these are useful for spotting the overall trend, but wheel loader demand varies meaningfully by region depending on local construction activity, aggregate and quarry operations, and municipal infrastructure spending. A market pulling back nationally on new equipment can still be running hot in a specific metro with active large-scale development, and vice versa. Before assuming the national trend applies directly to your market, it's worth checking in with your local dealer network about current lead times, incentive programs, and used inventory availability — national data sets the context, but local conditions determine your actual options.
Financing in This Market
Whichever side of the new-vs-used decision you land on, we structure equipment financing around your actual project pipeline and credit profile rather than a one-size-fits-all term sheet. That's especially important in a market where capital discipline is clearly the dominant theme — the right financing structure can make either a new or used purchase the smarter move, and we'll walk through the real numbers with you before you commit. Down payments range from $0 for well-qualified credit up to 20–40% depending on machine age and credit profile.
Ready to put this equipment to work?
Visit our homepage to see how BFC Equipment Loans helps contractors finance the iron that keeps jobs moving, apply for financing in minutes, browse our current equipment for sale, or subscribe to the blog for the next installment.


Comments